

Editorial Integrity
Making informed real estate decisions starts with having the right knowledge. At HomeAbroad, we offer US mortgage products for foreign nationals & investors and have a network of 500+ expert HomeAbroad real estate agents to provide the expertise you need. Our content is written by licensed mortgage experts and seasoned real estate agents who share insights from their experience, helping thousands like you. Our strict editorial process ensures you receive reliable and accurate information.
Non-US residents can qualify for a US mortgage through HomeAbroad, whether they live in the US or abroad.
HomeAbroad’s foreign national mortgage programs do not require an established US credit history.
Foreign national investors can choose between DSCR Loans, which qualify based on property rental income, and Full Documentation Loans, which use the borrower’s financial documentation.
Down payments start at 20% for Full Documentation Loans and 25% for DSCR Loans, depending on the loan program and borrower qualifications.
Non-US residents can qualify for a mortgage in the US, even if they live abroad or have recently moved to the country. HomeAbroad provides financing solutions for international buyers looking to purchase US real estate, with programs designed around their residency status, financial profile, and investment goals.
An established US credit history is not always necessary to secure financing. HomeAbroad’s foreign national mortgage programs allow eligible international borrowers to qualify using alternative methods, depending on the loan program. This guide explains who can qualify, what mortgage options are available, how the underwriting process works, and what borrowers should consider when financing US property.
Table of Contents
HomeAbroad Mortgage Solutions for Non-US Residents Inside and Outside the US
HomeAbroad specializes in US mortgages for international borrowers, and where you live does not decide whether you can apply.
If you live outside the US, HomeAbroad finances investment properties and second homes for buyers who hold a passport from another country, earn their income abroad, and have no US credit file. The loan is structured around the property or your home-country finances, and the transaction can be completed without traveling to the US.
If you live in the US on a work or study visa, HomeAbroad finances both a home to live in and investment property, including for newcomers whose US credit history is still too short for a conventional lender to price. In both cases the same loan team handles pre-qualification, underwriting, and closing, so an international borrower works with people who process these files every day.
The demand for US real estate among international buyers remains significant. According to the National Association of Realtors’ 2026 report, foreign buyers purchased $45.3 billion worth of US existing homes between April 2025 and March 2026, representing 67,100 property purchases. Of these transactions, 48% were all-cash purchases, compared with 28% among all US existing-home buyers.
Financing remains an option for international investors who want to purchase US property while preserving capital for other investments. HomeAbroad offers mortgage programs designed to support these buyers.
No Established US Credit History Required
A US credit history is the record of US loans and cards that produces a FICO score. Most US lenders price a loan from that score and cannot proceed without it. HomeAbroad’s foreign national programs do not rely on it.
HomeAbroad’s relevant foreign national mortgage programs do not require an established US credit history. Each program offers its own way to qualify instead: a DSCR loan is underwritten on the rental income of the property you are buying, while a Full Documentation Loan uses your income, assets, and credit record from your home country. Which path applies depends on the loan program and the purchase, and a HomeAbroad loan officer confirms the fit at pre-qualification.
Lucas Hernandez
Mortgage Loan Originator,
HomeAbroad
NMLS #2171747Not having an established US credit history does not automatically disqualify an international borrower from getting a mortgage. At HomeAbroad, we look at the loan program and evaluate factors such as the property’s rental income for DSCR loans, along with the borrower’s financial profile and available documentation where applicable. This allows qualified international investors to pursue US property financing without first building a US credit history
HomeAbroad Mortgage Options for Non-US Residents
HomeAbroad offers two foreign national programs, plus a path for borrowers who already have US credit.
DSCR Loan
A DSCR loan (Debt Service Coverage Ratio) qualifies the property rather than the borrower. HomeAbroad compares the property’s rental income with its monthly cost (principal, interest, taxes, insurance, and any association dues) and lends against that coverage. Your personal income, employment, and credit history in any country stay out of the equation.
This is the program most nonresident investors use. It fits a buyer abroad who wants a US rental property, and a visa holder in the US who wants to invest while their own credit file is still new. The property must be an investment property. You can find the latest DSCR Loan requirements, including down payment, reserve requirements, and loan amounts, on our DSCR loan for international investors page.
Full Documentation Loan
The Full Documentation Loan is the income-based alternative for buyers who prefer to qualify on their own finances, or whose purchase will not produce rent that covers the payment. HomeAbroad reviews foreign income, assets, and your home-country credit record in place of a US score. Explore our Full Documentation Loan page for details on qualification requirements, documentation, and available loan terms.
Conventional and FHA Loans for Borrowers With Established US Credit
Once a non-US resident living in the US has an established US credit history, conventional mortgages may become an option, often with a lower down payment than foreign national programs.
FHA loans, which are government-insured mortgages known for their lower down payment requirements, are no longer available to non-permanent residents, including most visa holders. Following the 2025 HUD eligibility changes, FHA loans are limited to US citizens and lawful permanent residents. Visa holders can explore conventional financing, if eligible, or HomeAbroad’s US Newcomer Mortgage program.
For a side-by-side view of when a DSCR loan beats waiting for conventional eligibility, see DSCR loan vs conventional loan for foreign nationals.
What to Expect on Rates and Down Payments
Foreign national mortgages are non-QM loans (outside the federal “qualified mortgage” rules that conventional and FHA loans follow), so the lender carries the risk that Fannie Mae, Freddie Mac, or FHA would otherwise absorb. That shows up as a higher down payment than a conventional primary-residence loan, a cash reserve requirement, and an interest rate above conventional pricing.
How far above depends on the program, the loan-to-value ratio, the property’s rent coverage, the property type, and the market on the day you lock. Current ranges and the factors that move them are on the foreign national mortgage rates page, and the foreign national mortgage calculator estimates a monthly payment from your purchase price, down payment, rate, and term. The calculator result is an estimate, not an approval.
How HomeAbroad Works With International Borrowers
HomeAbroad’s team works with borrowers across time zones, so the sequence is built around a buyer who may never visit the US before closing.
- Pre-qualification first. A HomeAbroad loan officer confirms which program fits and issues a pre-approval you can attach to an offer. For a DSCR loan this centres on the purchase price, property type, expected rent, down payment, and assets; income-based programs add income and credit documents.
- Property search and offer. HomeAbroad can connect you with a real estate agent experienced with international buyers.
- Underwriting. HomeAbroad orders the appraisal, which for a DSCR loan also establishes the rent figure, and coordinates title and insurance.
- Closing, including from abroad. Many HomeAbroad borrowers close without traveling, through a notarized power of attorney or remote online notarization where the state and title company allow it.
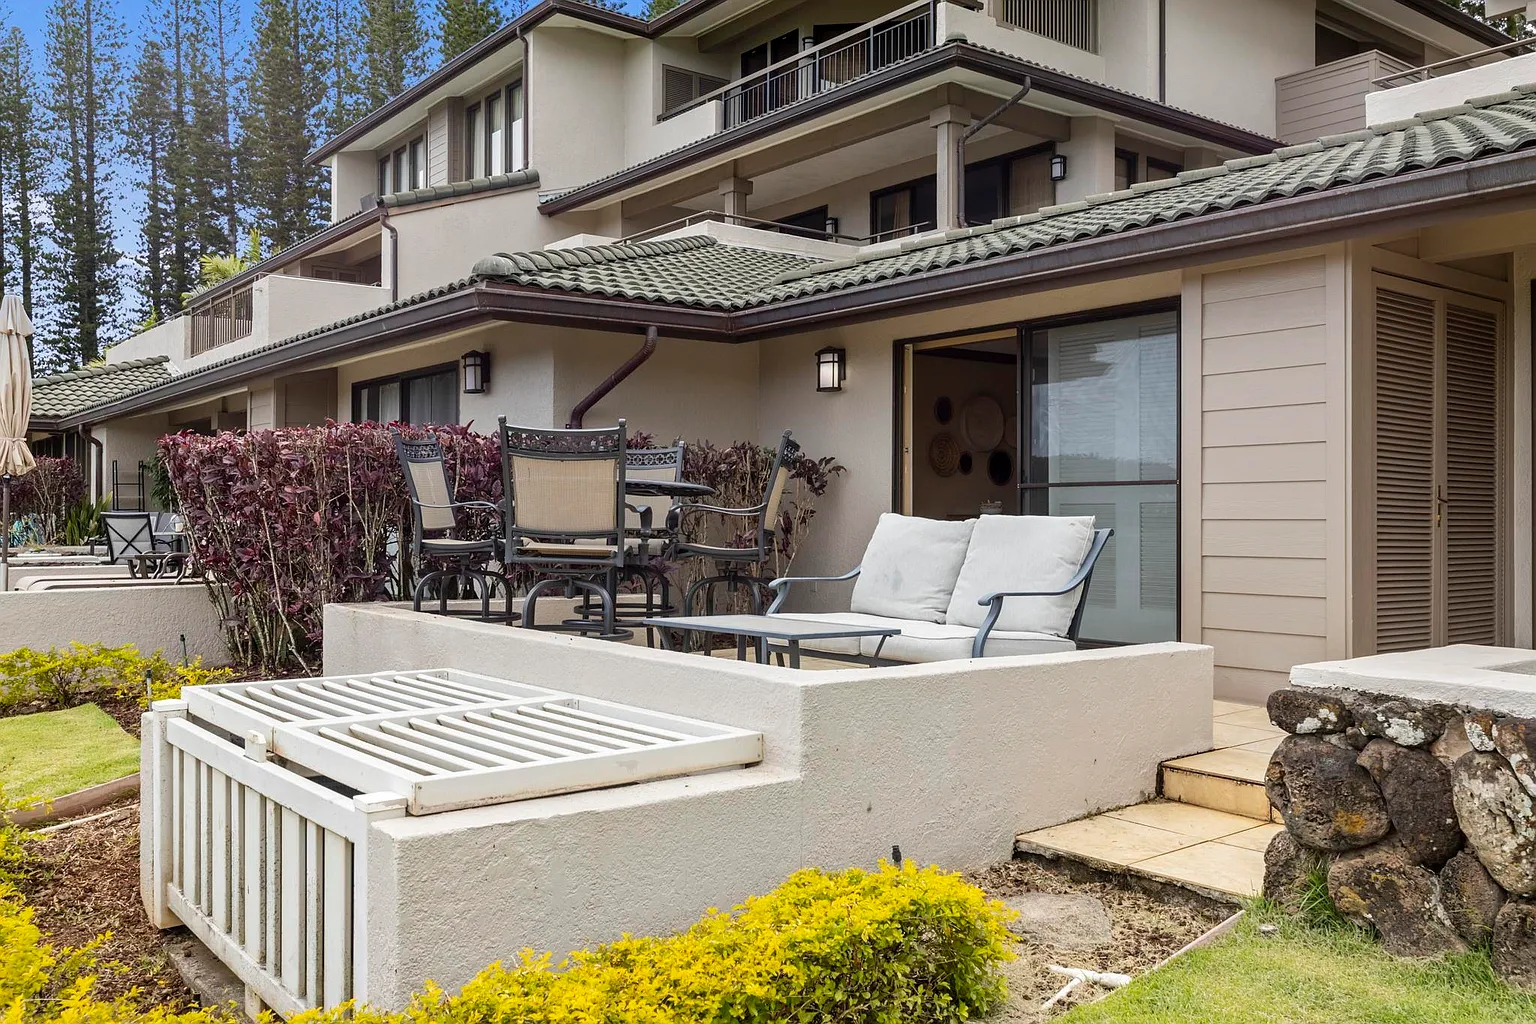
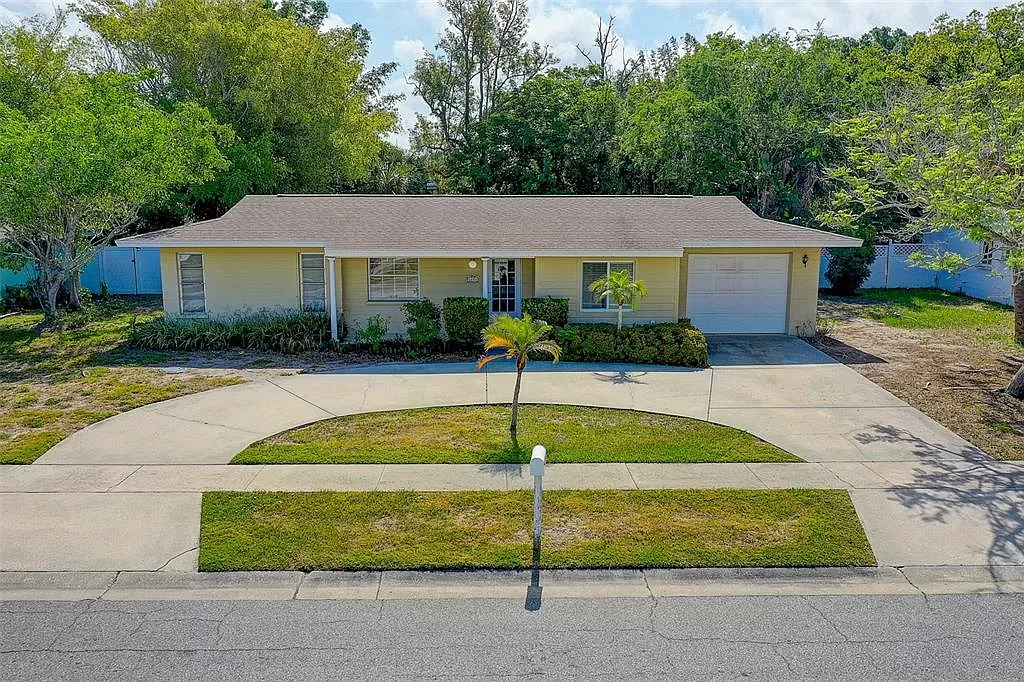
HomeAbroad’s lending arm is a licensed mortgage company, and a member of the Mortgage Bankers Association. Its published case studies show the programs in use: a UK investor’s DSCR loan in Florida with no US credit history, a Canadian couple’s Hawaii rental purchase, and an Israeli investor’s DSCR cash-out refinance.
Steven Glick
Director of Mortgage Sales · HomeAbroad
One common mistake I see is borrowers sending incomplete or unclear financial documents, particularly bank statements with missing pages or transactions that are difficult to verify. Complete, clearly organized documents help us review the file more efficiently.
For buyers living abroad who want the detail on taxes, LLC ownership, and remote transactions, the non-resident alien mortgage guide goes further. For the full no-US-credit how-to, see foreign national mortgage with no established US credit history.
See which HomeAbroad program fits your purchase. Pre-qualify as an international buyer, with no established US credit history needed for HomeAbroad’s foreign national programs.
Frequently Asked Questions
Can a non-US resident get a mortgage in the US?
Yes. HomeAbroad lends to non-US residents living inside or outside the US through its DSCR and Full Documentation programs, and neither requires an established US credit history.
Do I need a Social Security Number?
Not for HomeAbroad’s foreign national programs, which use a passport as the primary identity document.
Can I use funds from a foreign bank account?
Yes. HomeAbroad accepts assets held abroad for the down payment, closing costs, and reserves, documented with statements and reviewed for source of funds. Balances are converted to US dollars at underwriting.
What is the minimum down payment?
The minimum down payment depends on the loan program. HomeAbroad’s Full Documentation Loan starts at 20% down, while its DSCR Loan requires a minimum 25% down payment for foreign national investors. The exact requirement may vary based on the property, loan structure, and borrower qualifications. For more details, see our foreign national mortgage guide.