

Editorial Integrity
Making informed real estate decisions starts with having the right knowledge. At HomeAbroad, we offer US mortgage products for foreign nationals & investors and have a network of 500+ expert HomeAbroad real estate agents to provide the expertise you need. Our content is written by licensed mortgage experts and seasoned real estate agents who share insights from their experience, helping thousands like you. Our strict editorial process ensures you receive reliable and accurate information.
A DSCR loan qualifies you primarily based on rental income coverage, not W2s, paystubs, or US tax returns.
DSCR is typically calculated as gross monthly rent divided by PITIA, where PITIA reflects the full monthly housing payment.
HomeAbroad DSCR guidelines for foreign nationals include 25% down, purchase LTV up to 75%, and DSCR eligibility down to 0.75 in eligible scenarios.
HomeAbroad is a one-stop shop that makes the entire process simple for international real estate investors, helping you find properties using our AI-driven investment property search platform, get mortgages, set up a US-based LLC, open a local bank account, and handle paperwork required for closing.
A DSCR loan is a mortgage for a rental property that qualifies you on the property’s rental income rather than your personal income, tax returns, or established US credit history. DSCR stands for Debt Service Coverage Ratio: the property’s gross monthly rent divided by its full monthly housing payment. The stronger the ratio, the stronger the application, and ratios below 1.0 can still be considered with more equity in the deal.
For investors, that changes the question from “how much do I earn?” to “how much does the property earn?” It is why DSCR loans let you add properties without each one adding to a personal debt-to-income limit, and why they are the financing route most international investors use at HomeAbroad to buy US rental property.
This guide covers how the ratio is calculated, what HomeAbroad requires, what moves the rate, and how to apply, helping foreign investors understand the financing process and evaluate whether a DSCR loan is right for their investment.
Table of Contents
What is a DSCR Loan?
A DSCR loan, short for Debt Service Coverage Ratio loan, is an investment property mortgage where qualification is driven primarily by the property’s rental income and cash flow potential rather than your personal income documentation.
For foreign national investors, this is one of the most practical paths to financing because it reduces reliance on US-specific documentation like domestic credit history and tax filing continuity. HomeAbroad’s DSCR loan is tailored specifically for international real estate investors who may not have a US income or a US credit profile.
This innovative approach simplifies the process and makes DSCR loans an ideal choice for:
-
 Investors who want to separate personal finances from their investments.
- Borrowers are seeking a streamlined approval process that requires minimal documentation.
- Foreign nationals who may be first-time buyers or seasoned investors.
While DSCR loans are gaining popularity, many people, including industry professionals, are unfamiliar with how they work and how to calculate the DSCR.
Let’s break it down step by step.
How DSCR Loans Work
Understanding how DSCR (Debt Service Coverage Ratio) loans operate is crucial for real estate investors seeking financing options that prioritize a property’s rental income over personal income verification.
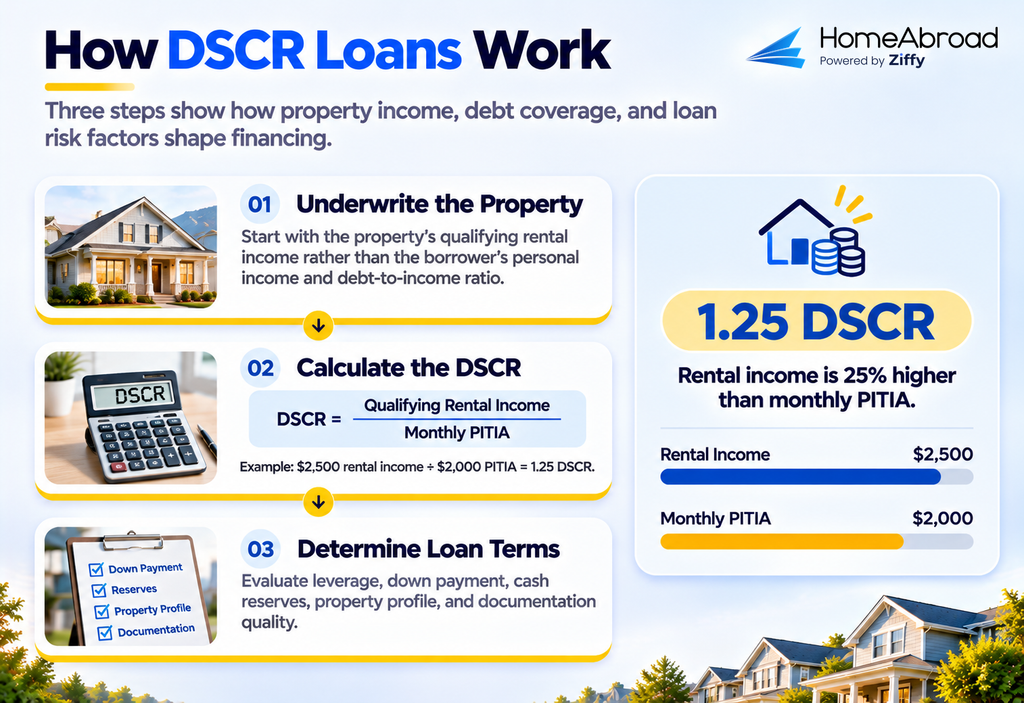
DSCR underwriting can be summarized in three steps:
1. The property is underwritten as an investment
Instead of starting with your personal income and debt-to-income ratio, DSCR underwriting starts with the rental property’s rental income ability to carry its own payment through rent.
2. The DSCR Ratio is calculated
The rent is divided by the full monthly housing payment, PITIA. A result of 1.25 means the property earns 25% more than the payment. A result of 0.90 means rent covers 90% of the payment and the owner funds the rest.
3. Terms follow the ratio and the other risk levers
The ratio sets the baseline, and the down payment, cash reserves, property type, and documentation quality shape the final terms. A higher ratio and a larger down payment generally bring the best pricing; a thinner ratio can still be eligible with more equity in the deal.
Let’s hear from Jay Thomas, a seasoned real estate agent, on the suitability of DSCR loans for investors.
Jay Thomas – Real Estate Agent (Source: BiggerPockets Forum)
You can check current DSCR loan interest rates to secure financing that aligns with your investment strategy.
DSCR Calculation, What PITIA Means, and What Counts As Rent
DSCR Formula used in rental properties:
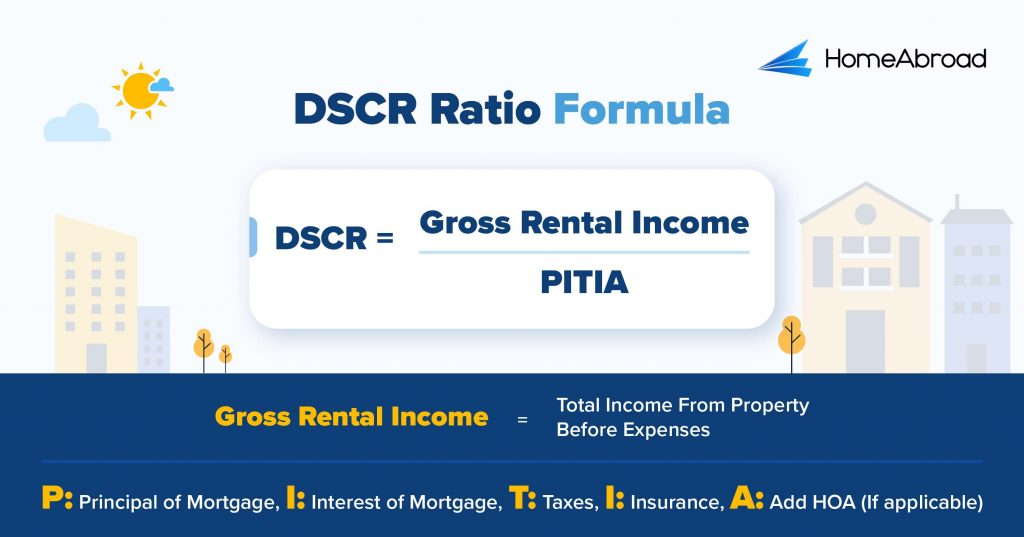
DSCR = Gross Monthly Rental Income / Monthly PITIA
What PITI means
PITI stands for principal, interest, taxes, and insurance, which are the four basic parts of a monthly mortgage payment.
Why HomeAbroad DSCR uses PITIA?
DSCR underwrites aim to reflect the full carry cost. That is why you will see PITIA used in DSCR explanations, because association dues can materially change the payment profile on condos and HOA-governed rentals.
What counts as rental income for DSCR
Most DSCR files support rent in one of two ways:
-
 The rent on a current signed lease, when the property is already tenanted.
- The market rent estimated in the appraisal, documented on a comparable rent schedule such as Fannie Mae Form 1007 (Single-Family Comparable Rent Schedule)
The second route matters for international buyers because a vacant, newly renovated, or newly purchased property can qualify before a tenant moves in. Rent estimates from listing portals are not used; the appraiser’s figure is, and it often comes in below online projections.
Let us understand DSCR ratio with the example of an Indian investor who bought an investment property in Memphis with HomeAbroad DSCR Loan:

Lucas Hernandez
Mortgage Loan Originator, HomeAbroad
Many of our clients come to us thinking traditional loan requirements limit them. Once we introduce them to DSCR loans and how we calculate the DSCR, it’s a game-changer. These loans make it easier for investors to focus on cash flow and grow their portfolios
How to Read Your Ratio
DSCR | What It Means | Eligibility at HomeAbroad |
|---|---|---|
1.00 or higher | Rent covers the full payment, with a cushion above 1.00 | Eligible; the best terms typically apply at 1.00 and above, and higher coverage prices lower |
Below 1.00 | Rent does not fully cover the payment | May be eligible with a larger down payment and a higher rate |
Run your own numbers with the DSCR loan calculator. It estimates the ratio from rent, price, down payment, rate, taxes, insurance, and HOA dues; the appraisal and underwriting decide the final figure.
HomeAbroad DSCR Loan Requirements for Foreign Nationals
At HomeAbroad, we’ve tailored our DSCR loan requirements to provide flexible financing solutions for foreign investors.
Whether you’re purchasing your first property or expanding your portfolio, our tailored criteria ensure that qualifying is straightforward and efficient.
Features | Requirements |
|---|---|
DSCR Ratio | >= 1 for best terms, <1 eligible with a higher down payment. We offer DSCR Loans for foreign nationals with a DSCR ratio as low as 0.75, which means you are eligible even if your rental property covers just 75% of the mortgage. |
Credit Score | No US Credit History Required |
Down Payment | 25% |
LTV Ratio | Purchase: Up to 75% |
Cash Reserves | 6 Months |
Property Use | Investment properties (residential and commercial) |
Loan Amount | >= $100k |
DSCR Loan Options: Purchase, Rate and Term Refinance, Cash-out Refinance
DSCR is not a single use loan. It is a qualification method that can apply across common investor transactions.
DSCR purchase
Used when you are buying an income-producing rental and want underwriting tied to rent coverage rather than personal income.
DSCR rate and term refinance
Used when you want to replace an existing mortgage with new terms, typically without pulling out significant equity. HomeAbroad’s DSCR LTV guidelines show rate and term refinance up to 75% in eligible scenarios.
DSCR cash-out refinance
Used when you want to tap equity and redeploy capital into another investment. HomeAbroad’s DSCR loan allows cash-out refinance up to 70% LTV in eligible scenarios.
Property Use: What Types of Rentals Work Best with DSCR
From an investor standpoint, DSCR works best when the rent story is clean and supportable.
Strong DSCR candidates often include:
- Long-term rentals with clear market rent support
- Standard 1 to 4 unit residential rentals
- Condos and townhomes where HOA rules support rental use and dues are clearly accounted for in the carry cost
HomeAbroad’s DSCR program is positioned for investment properties across residential and commercial categories, so the key is not the label, it is the rent support and execution path.
DSCR Loans for Short-Term Rentals
DSCR loans for short-term rentals, like Airbnb, can work, but the critical question becomes: what income basis is the lender willing to underwrite.
A Quick 7-Step Guide to Applying for a DSCR Loan
1. Get Started with HomeAbroad
Choosing the right DSCR loan lender is crucial. HomeAbroad specializes in DSCR loans, offering tailored loan terms to maximize your investment returns.
With our proven track record of working with international real estate investors and our expertise in DSCR loans, we are committed to helping you achieve your real estate investment goals. Begin your DSCR loan journey with us.
Not sure about us? Liam and Emma can vouch for us:
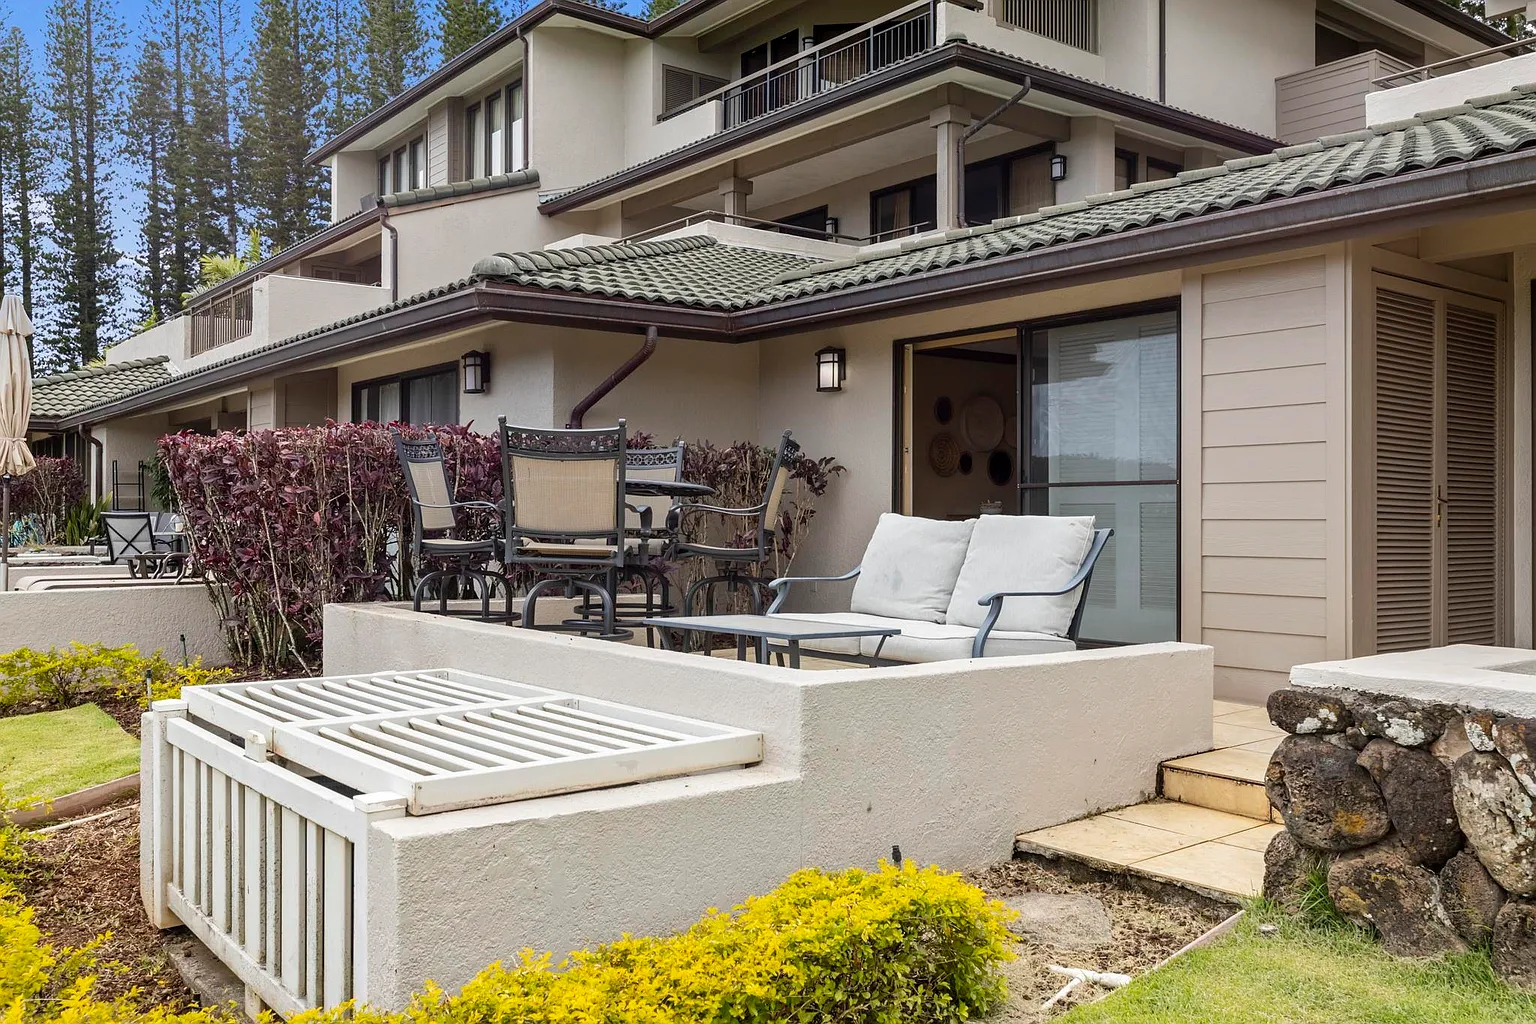
Despite having no US credit history, they guided us to the perfect DSCR loan, allowing us to invest in a stunning property in Lahaina. The process was smooth, and the rental income is covering our mortgage. We couldn’t be happier with their expert support and highly recommend them to any foreign national looking to invest in the US.
Liam and Emma – Canadian Investor – Purchased a rental property in Hawaii.
You can read about Liam and Emma’s homebuying journey here.
2. Meet with Our Mortgage Officers
After you submit your details, our dedicated mortgage officer will promptly contact you and guide you through every step of the process.
At HomeAbroad, we prioritize your investment success and are dedicated to providing personalized support tailored to your needs.
3. Get Preapproval
Submit basic financial information to get preapproved for a DSCR loan, giving you an idea of how much you can borrow based on your available assets for a down payment, reserves, and expected closing costs.
4. Gather Your Documents and Fill Out an Application
Collect necessary documents, including rental agreements, financial statements, and property details, and complete the loan application.
Required Documents for DSCR Loans:
- Property’s purchase contract
- 2 Months’ Bank Statements
- 1007 Rent Schedule
- Homeowners Insurance
- Entity Documentation (If buying under LLC)
5. Underwriting
To make a final decision, the underwriter will thoroughly evaluate your application and supporting documents in accordance with the lending guidelines.
6. Approval
The underwriter will either approve, decline, or accept your loan application with conditions.
7. Closing
After approval, our loan officer will provide a closing disclosure that includes your final loan terms, your monthly mortgage payment schedule, and the closing costs you are required to pay on closing day. Accept it and complete the necessary paperwork to receive the funds and take ownership of the property.
By following these steps and meeting the outlined criteria, you can qualify for a DSCR loan and leverage its benefits to grow your real estate investment portfolio.
Here’s what our Mortgage Officer, Steven Glick, has to say about DSCR Loans:
Jeff Larrabee
Senior Customer Loan Specialist, HomeAbroad
My clients value the flexible underwriting guidelines associated with a DSCR loan, along with the built-in investment protection. DSCR provides peace of mind because investors are confident they are obtaining financing on a property that will offer immediate positive cash flow potential.
Pros and Cons of DSCR Loans
The downsides of a DSCR loan are the price of the flexibility: higher rates than an owner-occupied mortgage, a larger down payment, documented reserves, and often a prepayment penalty. Set against what the loan removes, the trade-offs look like this:
PROS | CONS |
|---|---|
No Personal Income Verification; loan underwritten based on the property’s rental income | Rates are generally higher than owner-occupied mortgage rates and often above conventional investment loan rates |
Get Multiple DSCR Loans Simultaneously | 25% minimum down payment, higher than some domestic investor programs |
Fast and Streamlined Process; loan approval within 30 days | Additional Closing Costs |
Flexible Loan Options; DSCR ratio as low as 0.75 accepted | Risk with Low Cash Flow |
Cash-Out and Refinance Options | |
Versatility in Property Use |
DSCR Loans Compared With Conventional Investment Loans
If you have US income and an established US credit profile, you may be able to choose between a DSCR loan and a conventional investment property loan. The question is which one qualifies more of what you want to buy.
Situation | Likely Better Fit |
|---|---|
No US income, no US credit history, buying from abroad | DSCR loan |
Strong rent coverage on the target property | DSCR loan |
Building a multi-property portfolio | DSCR loan, since DTI does not accumulate |
Stable US W-2 income, strong US credit, one or two properties | Conventional may price lower |
DSCR Loan Success Story: How a UK Investor Achieved Their US Real Estate Goals
Over the years, I have worked with international real estate investors, and I’ve seen firsthand the unique challenges they face when entering the US real estate market. However, at HomeAbroad, we specialize in turning these challenges into opportunities.
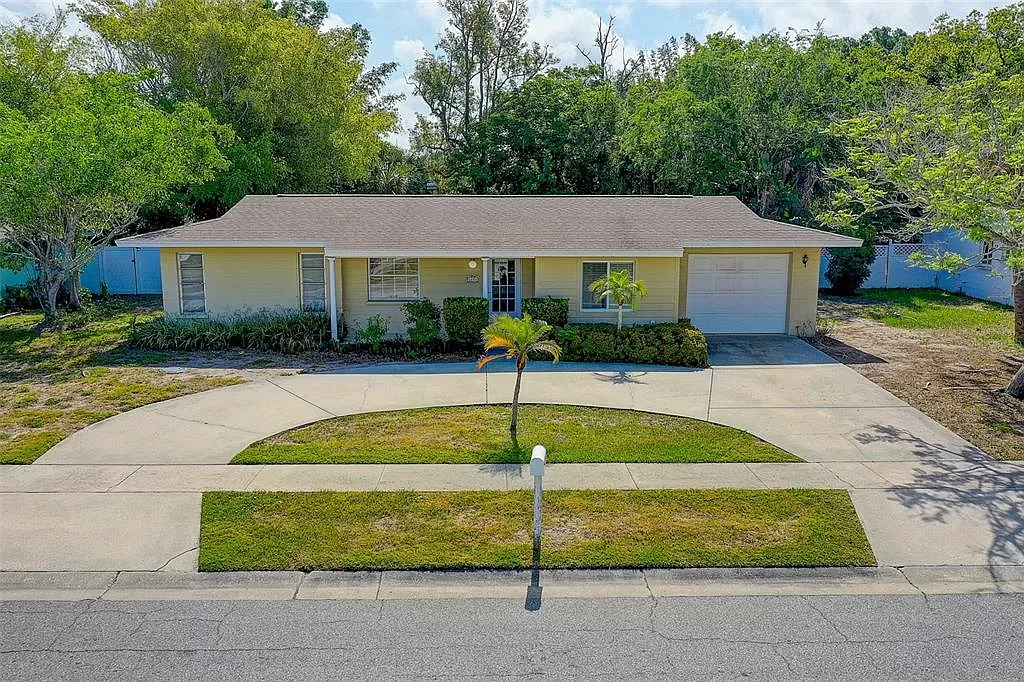
One such success story is that of a UK investor who secured a DSCR loan to purchase a rental property in Florida.
This case perfectly highlights how tailored solutions, expert guidance, and a deep understanding of DSCR loan flexibility can make all the difference for foreign investors.
Overview:
Client Profile

Name: Sam Smith (name changed for privacy)
Background: A UK citizen on an L1 visa with less than six months in the US and no US credit history.
Objective: Purchase a $500,000 rental property in Sarasota, Florida, to generate steady cash flow and build a US real estate portfolio.
Challenges

No US Credit History: Sam faced multiple rejections from traditional lenders due to their lack of a US credit score, a common obstacle for foreign nationals.
Low DSCR: The rental property had a DSCR below 1, which typically disqualifies it for traditional DSCR loan programs.
Understanding US Financing Requirements: As a foreign national, Sam was unfamiliar with the US loan application process and documentation requirements.
The HomeAbroad Solution
HomeAbroad’s expert mortgage officer, Steven Glick, tailored the DSCR loan program to craft a perfect solution ideally suited to Sam’s needs:
- Identifying the Right Loan Program: Recognizing the limitations of traditional lenders, our mortgage officer, Steven Glick, recommended a no-ratio DSCR loan, which does not require a specific DSCR for approval.
- Customizing the Process: Steven simplified the application process for Sam by guiding them through every step, including understanding property performance metrics and submitting essential documents.
- Efficient Underwriting: Despite the property’s low DSCR and Sam’s lack of credit history, our tailored approach ensured a smooth underwriting process, culminating in loan approval within 29 days.
The Outcome
With HomeAbroad’s support, Sam successfully purchased the $500,000 rental property under an LLC and secured the following loan terms:
- Loan Amount: $341,000
- Loan Type: No-ratio DSCR loan
- Time to Close: 29 days
Sam is now generating rental income from the property and has laid the foundation for an expanding US real estate portfolio.
Why This Case Matters
This success story underscores the flexibility and power of DSCR loans, particularly for foreign nationals. At HomeAbroad, our expertise in working with global investors ensures that challenges like a lack of US credit history or low DSCR don’t stand in the way of your investment goals.
Get Started and Apply for a DSCR Loan Today
Debt Service Coverage Ratio (DSCR) loans have revolutionized real estate financing by eliminating the traditional hurdles of income verification and credit history. Instead, they focus on the property’s rental income potential, making them the ultimate tools for scalable, flexible investments.
With over 10 years of experience in helping global investors leverage DSCR loans, I can confidently say this financing strategy is a game-changer for building a strong US real estate portfolio. At HomeAbroad, we take pride in being at the forefront of DSCR lending, offering tailored loan solutions designed to meet the unique needs of international buyers and US newcomers.
But our support goes far beyond financing. As a one-stop PropTech and FinTech platform, HomeAbroad simplifies every aspect of purchasing and managing US real estate. Alongside DSCR loans, we provide:
- Now, you can use HomeAbroad’s AI-powered investment property search platform to find investment-ready homes.
- Access to 500+ expert US real estate agents for personalized guidance.
- Concierge services including LLC formation, US bank account setup, and homeowner’s insurance.
- Property management coordination to ensure your investments are stress-free and profitable.
Whether you’re a seasoned investor or just entering the US real estate market, HomeAbroad equips you with the tools, expertise, and ongoing support to succeed.
Ready to take your investments to the next level? Contact us today and let our experts guide you every step of the way.
Pre-qualify for a DSCR Loan in a Few Clicks.
No Paystubs, W2s, or Tax Returns Required.

Questions HomeAbroad Team Gets Asked By Investors Regarding DSCR Loan – FAQs
Can I use future rental income to qualify for a DSCR loan?
Yes, if the property is not currently rented, we can use the appraised market rent value to calculate the DSCR. This is particularly useful for newly acquired properties or those undergoing transition. However, documentation such as a rental market analysis or appraisal report will be required.
Can you qualify for a DSCR loan with a DSCR less than 1?
Yes. HomeAbroad may consider DSCR loans with a ratio below 1.0 for eligible properties. However, these loans typically require a larger down payment and may carry a higher interest rate. Final eligibility and terms depend on the property’s cash flow and overall loan scenario.
Are there any restrictions on the types of properties I can finance with a DSCR loan?
DSCR loans are highly versatile and can be used to finance a variety of properties, including:
Single-family homes
Multi-family units
Short-term rentals such as Airbnb and Vrbo
However, properties must be intended for investment purposes, not primary residences or second homes.Do I need a good credit score for DSCR loans?
DSCR loans focus on the property’s rental income, rather than personal income verification. Foreign investors can qualify for a DSCR loan without a US credit history.
Can I use DSCR loans for property flipping?
DSCR loans are not designed for short-term flipping because they focus on rental income rather than the property’s resale value. However, if you plan to hold the property as a rental after renovations, a DSCR loan can be a viable option. For property flipping, you can check out HomeAbroad’s Fix and Flip loans.
Is cash-out refinancing available for DSCR loans?
Yes, HomeAbroad offers cash-out refinancing options for DSCR loans, allowing investors to extract equity from their properties for further investments or renovations.
What are the interest rates for DSCR loans?
DSCR loan interest rates vary based on market conditions, borrower profiles, and property type, but are typically higher than conventional loan rates. However, HomeAbroad offers competitive rates that enable investors to leverage property cash flow to achieve better returns.
At HomeAbroad, we ensure the reliability of our content by relying on primary sources such as government data, industry reports, firsthand accounts from our network of experts, and interviews with specialists. We also incorporate original research from respected publishers when relevant. Discover more about our commitment to delivering precise and impartial information in our editorial policy.
- Investopedia: Debt Service Coverage Ratio: How to Use and Calculate It
- What Is a Homeowners Association (HOA), and How Does It Work?
- Consumer Financial Protection Bureau: What is a debt-to-income ratio?
- Fannie Mae: 1007 Rent Schedule